Sheffield does not get the same attention as Manchester or Leeds when investors talk about UK short-let property, and that relative obscurity is part of what makes it interesting. The city has a large, diverse visitor economy, two major universities, and a regenerating city centre, but demand is patchy enough that the wrong property in the wrong postcode will underperform badly. This guide cuts through the headline numbers and explains what the market actually looks like from an operator's perspective.
Why Sheffield is on investors' radars
Sheffield is the fourth largest city in England by population, with around 556,000 residents, and it draws a steady stream of visitors for a wider range of reasons than most people realise. The city hosts major events at the Sheffield Arena (now the Utilita Arena), attracts climbing and outdoor sports enthusiasts heading to the Peak District, and generates consistent corporate demand from businesses clustered around the Advanced Manufacturing Research Centre in Rotherham, which sits just outside the city boundary but uses Sheffield as its accommodation base.
Student and parent visits are substantial year-round. The University of Sheffield and Sheffield Hallam together enrol roughly 60,000 students, and parents travelling for open days, graduations and moving-in weekends fill properties that hotels cannot accommodate well. That is a demand driver that shows up clearly in occupancy data for well-located apartments in S1, S2 and S10.
Property prices remain meaningfully lower than comparable northern cities. A two-bedroom apartment in Sheffield city centre can often be acquired for £160,000 to £200,000, against £220,000 to £270,000 for a similar unit in central Manchester. That lower entry cost compresses the revenue you need to justify the investment, which improves the risk-adjusted case considerably.
Which areas in Sheffield perform best for short lets
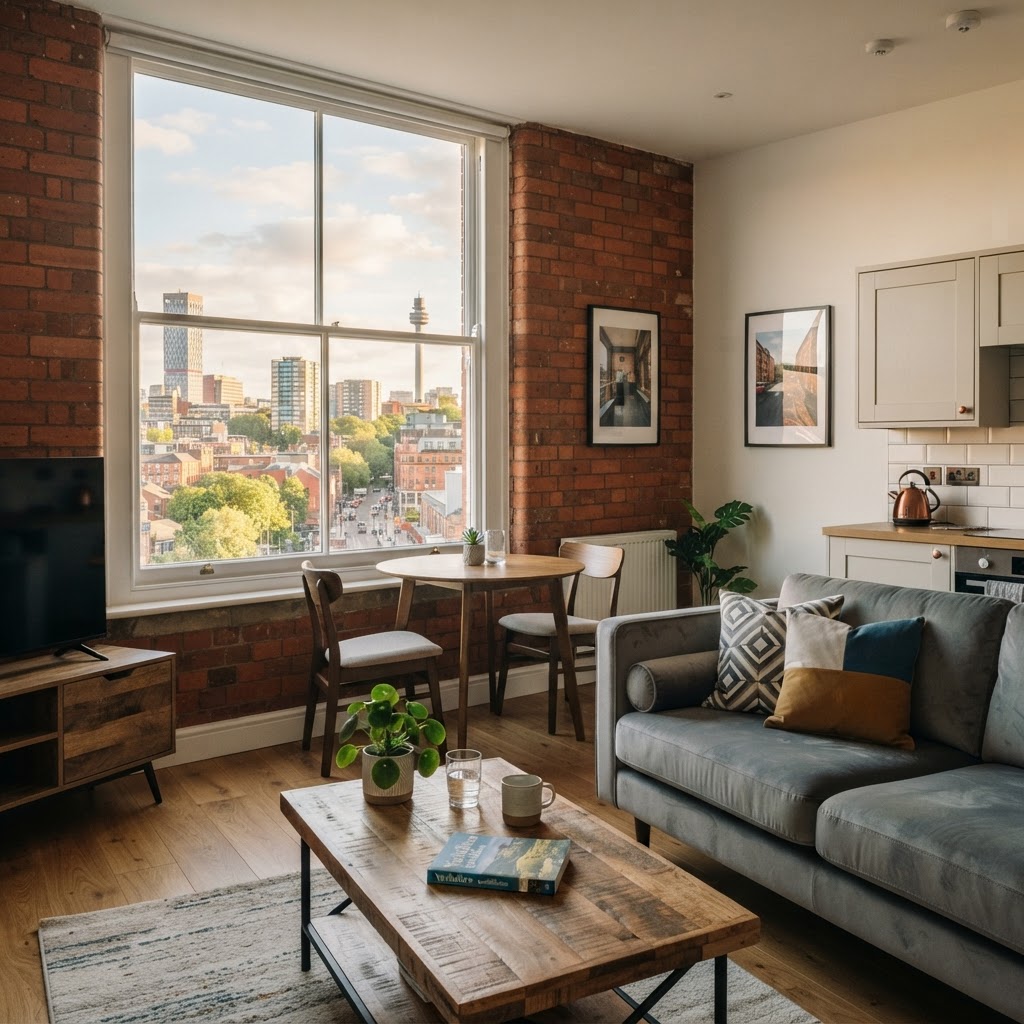
The city centre postcodes S1 and S2 are the most straightforward areas to operate in. Properties within walking distance of Sheffield station, the Winter Gardens and the Crucible Theatre attract leisure visitors, theatre-goers during the World Snooker Championship in April and May, and business travellers who want city-centre convenience. Occupancy in well-presented S1 apartments regularly runs between 72% and 82% across the year, with April being the single strongest month due to the snooker.
Kelham Island and Neepsend, sitting just northwest of the centre, have become Sheffield's most talked-about hospitality and leisure districts. A cluster of independent bars, restaurants and the Kelham Island Museum draw weekend visitors specifically to this area, and short-let properties here can command a small premium over equivalent units in the generic city centre. The challenge is that residential supply in Kelham Island is still relatively limited, so finding the right property takes patience.
The S10 postcode, covering Broomhill and Fulwood on the western edge of the city, is less obvious but worth understanding. It sits close to the University of Sheffield's main campus and the Royal Hallamshire Hospital, which generates medical contractor stays of three to seven nights — exactly the kind of booking that lifts weekly revenue and reduces the cleaning frequency that erodes margins. Properties here tend to be Victorian terraces and larger apartments rather than new-build units, and they photograph well.
Areas to be more cautious about include S4 (Burngreave) and parts of S5, where leisure demand is low and the corporate market thin. Short lets in those postcodes rely almost entirely on relocation and insurance contractor bookings, which can work but require a very specific operating approach and do not suit owners who want flexible personal use.
What can you realistically earn on Airbnb in Sheffield
A well-managed, well-presented one-bedroom apartment in S1 or Kelham Island will typically generate between £18,000 and £24,000 gross revenue per year. A two-bedroom property in the same locations tends to produce £24,000 to £32,000, depending on quality and pricing strategy. These figures assume active dynamic pricing, a strong listing with professional photography, and consistent review management — not a set-and-forget approach.
Average daily rates in Sheffield sit noticeably below Manchester and Leeds. Midweek rates for a one-bedroom in the city centre typically run between £75 and £95, rising to £110 to £140 on weekends and significantly higher during the snooker. That compressed ADR means occupancy really matters here — you cannot rely on a handful of premium-rate nights to carry the month the way you might in a city with a stronger events calendar.
One figure that does not show up in public data tools: Sheffield has a notably high proportion of longer stays (four to ten nights) compared to cities like Liverpool or Edinburgh. From properties we have managed in the city, roughly 35% of bookings fall into that mid-length category, driven by the medical and academic visitor segments. Longer stays reduce turnover costs, which meaningfully improves net yield even when headline revenue looks modest against other cities. If you want to understand how dynamic pricing tools can help you capture rate on shorter stays without sacrificing that mid-length demand, our pricing resources cover the approach in detail.
The risks and challenges specific to Sheffield
Sheffield's event calendar is thin outside the World Snooker Championship. Unlike Leeds or Birmingham, the city does not have a consistent flow of stadium concerts, large-scale conferences or international sporting fixtures filling gaps in leisure demand. That means revenue seasonality is more pronounced, with Q1 (outside the snooker) being genuinely slow, and operators need to plan cash flow accordingly.
The new-build apartment market in Sheffield city centre has grown considerably in the last five years, and a significant number of those units are operating as short lets. In buildings like those around Furnival Gate and the Eye Witness Works development, supply concentration can soften rates during quiet periods. Buying into a development that already has twenty short-let units is a different proposition to operating a standalone property in a mixed residential street.
Sheffield City Council has not yet introduced specific short-let licensing or registration requirements beyond the national position, but the broader UK short-let registration scheme is progressing. Operators should stay informed and, if you have questions about how planning or licensing rules apply to your specific property, take advice from a solicitor or planning consultant rather than relying on general guidance.
Short-let vs long-let in Sheffield: which makes more sense
Long-let yields in Sheffield are competitive by UK standards. A two-bedroom apartment in S1 might achieve £900 to £1,050 per month on a standard assured shorthold tenancy, giving a gross yield of around 5.5% to 6.5% on a £180,000 purchase. That is a solid baseline, and for investors who want simplicity or who are not based locally, long-let is an entirely rational choice in this city.
Short-let outperforms long-let in Sheffield when the property is in the right location, presented to a high standard, and actively managed. In those conditions, the same two-bedroom apartment generating £1,000 per month on long-let might produce £2,200 to £2,600 per month gross on short-let, with management fees, cleaning and consumables reducing net income but still leaving a meaningful premium. The gap is real but narrower than in cities like Edinburgh or London, so the decision comes down to how much operational complexity you want to take on or pay someone else to handle.
Properties with three or more bedrooms in walkable city-fringe areas (S10, S11 Ecclesall Road corridor) tend to show the strongest short-let premium, because large groups visiting for weekends, stag and hen parties and family events have very few hotel alternatives that suit them. That segment also books further in advance, which smooths occupancy forecasting.
What to look for before you buy
Before committing to a Sheffield short-let purchase, there are a few things worth checking that go beyond the standard investment analysis.
Check the lease: many Sheffield city-centre apartments are leasehold, and a growing number of freeholders are inserting clauses that restrict or prohibit short-term letting. Always have a solicitor review the lease before exchange.
Confirm the building's management position: some developments have managing agents who impose additional requirements or restrictions on short-let operators, including insurance obligations and guest registration.
Assess parking and access: Sheffield is a car-dependent city compared to Manchester or Leeds, and properties with parking or within easy reach of a public car park consistently outperform those without, especially for weekend leisure guests.
Review the local competition properly: use AirDNA or a similar data source to check actual occupancy and ADR for comparable listings in the same postcode, not city-wide averages.
It is also worth speaking to a local letting agent who operates across both long-let and short-let, because they will have a realistic picture of void periods and maintenance costs that data tools do not capture. Sheffield has some quirks in terms of contractor availability and cleaning capacity that affect operating costs, particularly in the S10 area where the pool of reliable short-let cleaners is smaller than in the city centre.
For a broader framework on how to stress-test a short-let acquisition before you commit, the investment analysis guide covers the key metrics in detail. And if you are looking at other northern cities for comparison, our guides to Manchester and Leeds are worth reading alongside this one.
If you own or are considering buying a property in Sheffield and want to understand what it could realistically earn as a short let, Truestays offers a free, no-obligation income estimate based on your specific postcode, property type and specification. There is no commitment involved — just a clearer set of numbers to work with.
Ready to get started?
Get a free personalised income estimate for your property. No commitment, no pressure.